Insurance
Underinsurance: The Clause That Reduces Every Claim
If the sum insured is too low, the insurer can cut a partial claim by the same proportion. It applies to losses of any size.
How cover is priced, where claims fail, and which policies are worth holding — assessed on the wording rather than the advert.
If the sum insured is too low, the insurer can cut a partial claim by the same proportion. It applies to losses of any size.
Standard home cover frequently lapses once building work starts or the property is left empty.
Convenient and sometimes cheaper. The saving depends entirely on the mix of drivers and vehicles.
Pays a regular income when illness or injury stops you working. Broader in scope than critical illness cover.
Covers injury or damage you cause to others while working. Frequently required by clients before they will engage you.
Specialist policies use agreed value and mileage limits, and cost considerably less than standard cover for the same vehicle.
Standard home cover excludes both periodic vacancy and paying guests. They are different risks needing different policies.
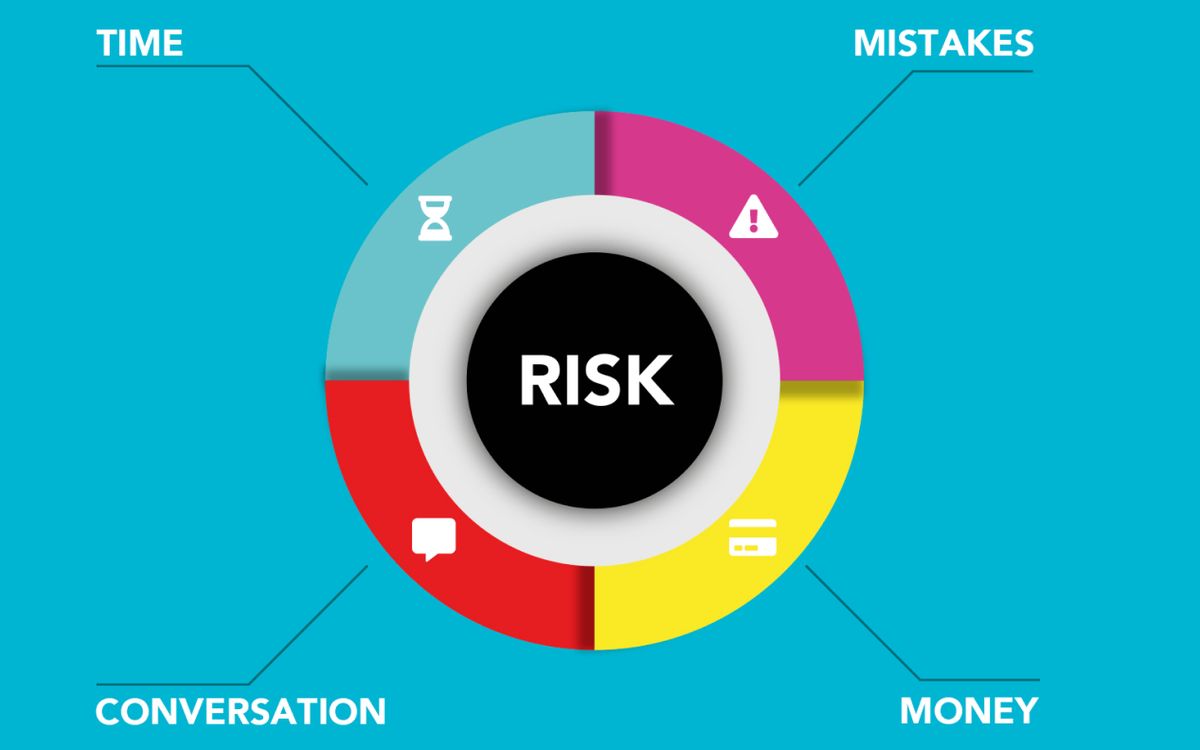
Commonly bundled with home or motor policies and rarely read. Useful within limits, with significant conditions.
Which policies matter depends on what you do and what your contracts require. Several are commonly overlooked.
The first offer is a starting position based on trade guides. Evidence of comparable vehicles moves it.